
Membership-only discount retailer Costco (NASDAQ:COST) reported revenue ahead of Wall Street’s expectations in Q3 CY2026, with sales up 11.1% year on year to $95.72 billion. Its GAAP profit of $6.75 per share was 3.4% above analysts’ consensus estimates.
Is now the time to buy Costco? Find out by accessing our full research report, it’s free.
Costco (COST) Q3 CY2026 Highlights:
- Revenue: $95.72 billion vs analyst estimates of $94.85 billion (11.1% year-on-year growth, 0.9% beat)
- EPS (GAAP): $6.75 vs analyst estimates of $6.53 (3.4% beat)
- Operating Margin: 4%, in line with the same quarter last year
- Free Cash Flow Margin: 2.6%, similar to the same quarter last year
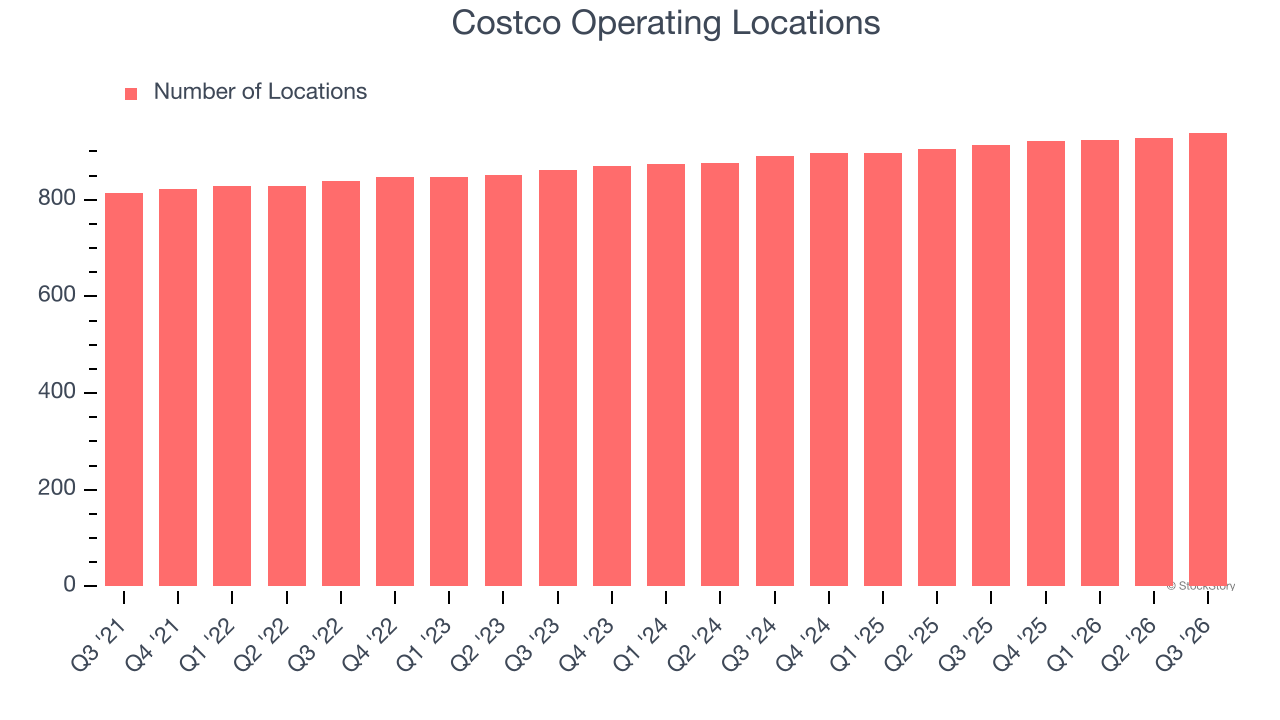
- Locations: 939 at quarter end, up from 914 in the same quarter last year
- Same-Store Sales rose 9.4% year on year (5.7% in the same quarter last year)
- Market Capitalization: $401.2 billion
Company Overview
Designed to be a one-stop shop for the suburban consumer, Costco (NASDAQ:COST) is a membership-only retail chain that sells groceries, apparel, toys, and household items, often in bulk quantities.
Revenue Growth
A company’s long-term performance is an indicator of its overall quality. Even a bad business can shine for one or two quarters, but a top-tier one grows for years.
With $303.2 billion in revenue over the past 12 months, Costco is a behemoth in the consumer retail sector and benefits from economies of scale, giving it an edge in distribution. This also enables it to gain more leverage on its fixed costs than smaller competitors and the flexibility to offer lower prices. However, its scale is a double-edged sword because there are only a finite number of places to build new stores, making it harder to find incremental growth. To expand meaningfully, Costco likely needs to tweak its prices or enter new markets.
As you can see below, Costco’s sales grew at a mediocre 7.8% compounded annual growth rate over the last three years, but to its credit, it opened new stores and increased sales at existing, established locations.
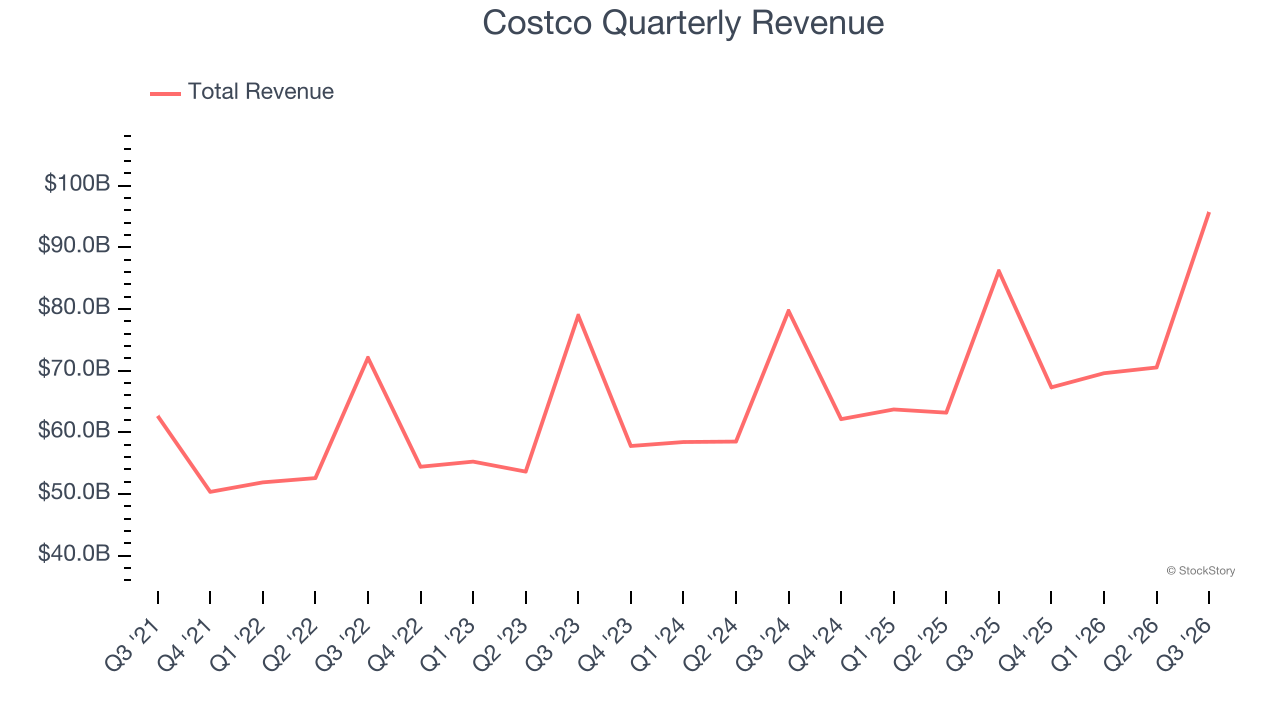
This quarter, Costco reported year-on-year revenue growth of 11.1%, and its $95.72 billion of revenue exceeded Wall Street’s estimates by 0.9%.
Looking ahead, sell-side analysts expect revenue to grow 8% over the next 12 months, similar to its three-year rate. This projection is particularly noteworthy for a company of its scale and indicates the market sees success for its products.
ONE MORE THING: 3 Hidden Platforms Growing 3X Faster than Amazon, Google, and PayPal. Amazon, Google, and Meta all followed the same playbook: Dominate an ignored market. Build an unbeatable moat. Scale until you’re unstoppable.
These three platforms are running that exact playbook right now. The early investors in Amazon made fortunes. The early investors in these could do the same. Get All 3 Stocks Here for FREE.
Store Performance
Number of Stores
The number of stores a retailer operates is a critical driver of how quickly company-level sales can grow.
Costco operated 939 locations in the latest quarter. It has opened new stores quickly over the last two years, averaging 2.8% annual growth, faster than the broader consumer retail sector.
When a retailer opens new stores, it usually means it’s investing for growth because demand is greater than supply, especially in areas where consumers may not have a store within reasonable driving distance.
Same-Store Sales
The change in a company’s store base only tells one side of the story. The other is the performance of its existing locations and e-commerce sales, which informs management teams whether they should expand or downsize their physical footprints. Same-store sales provides a deeper understanding of this issue because it measures organic growth at brick-and-mortar shops for at least a year.
Costco has been one of the most successful retailers over the last two years thanks to skyrocketing demand within its existing locations. On average, the company has posted exceptional year-on-year same-store sales growth of 7.1%. This performance suggests its rollout of new stores is beneficial for shareholders. We like this backdrop because it gives Costco multiple ways to win: revenue growth can come from new stores, e-commerce, or increased foot traffic and higher sales per customer at existing locations.
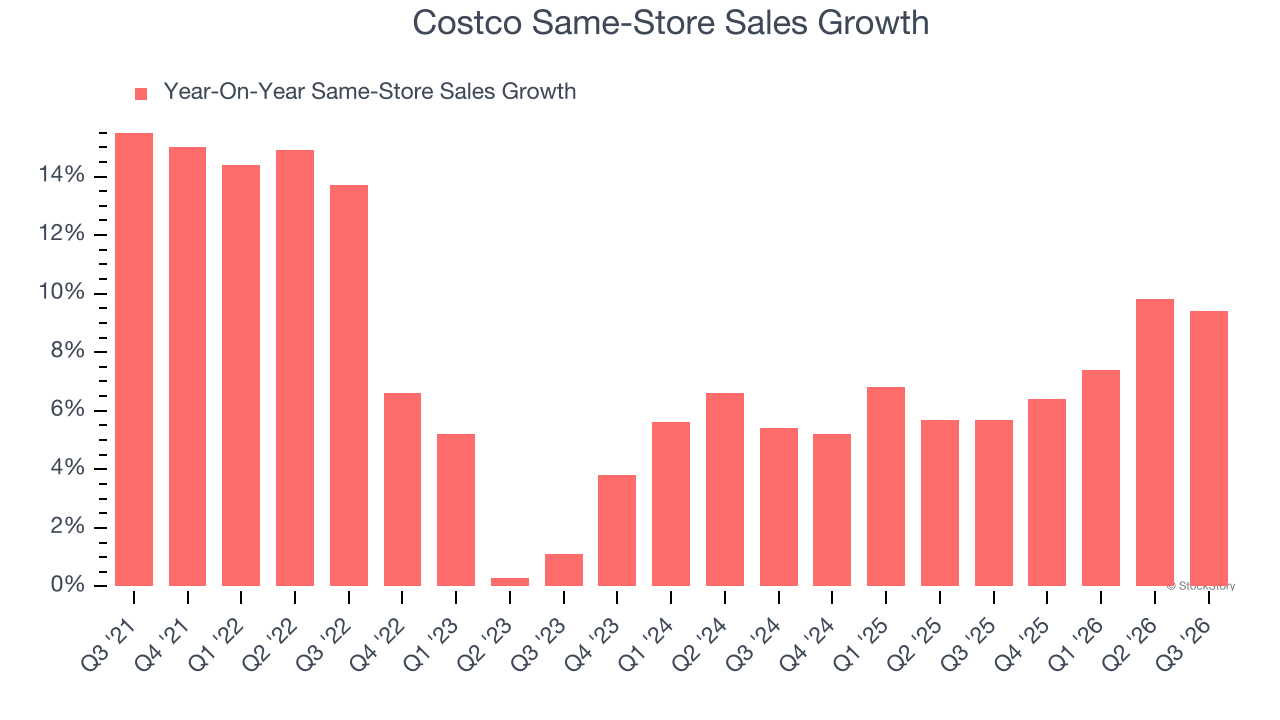
In the latest quarter, Costco’s same-store sales rose 9.4% year on year. This growth was an acceleration from its historical levels, which is always an encouraging sign.
Key Takeaways from Costco’s Q3 Results
We were impressed by how significantly Costco blew past analysts’ gross margin expectations this quarter. We were also happy its revenue narrowly outperformed Wall Street’s estimates. Overall, this print had some key positives. The stock remained flat at $898.75 immediately following the results.
Costco had an encouraging quarter, but one earnings result doesn’t necessarily make the stock a buy. Let’s see if this is a good investment. What happened in the latest quarter matters, but not as much as longer-term business quality and valuation, when deciding whether to invest in this stock. We cover that in our actionable full research report which you can read here (it’s free).